
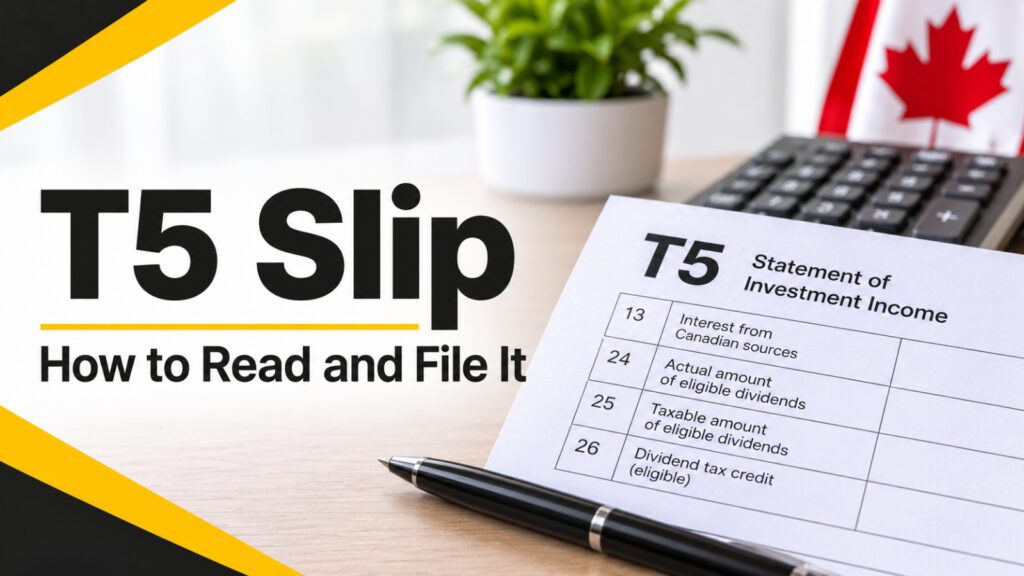
A T5 slip, officially the Statement of Investment Income, reports interest, dividends, and certain other investment income paid to you during the year. Banks, brokerages, and corporations issue them, and you report the amounts on your tax return.
Sounds simple. Until you open one and see boxes labelled “actual amount,” “taxable amount,” and “dividend tax credit” with three different numbers for the same dividend.
- What a T5 slip is (and what it isn’t)
- How to read the key boxes
- How to report a T5 on your return
- How business owners issue T5 slips
- Common T5 mistakes and fixes
Whether you’re receiving T5s or issuing them from your own corporation, our personal tax services make sure every box lands on the right line. No guesswork, no CRA follow-up letters.
What a T5 Slip Is (and Isn’t)
A T5 tracks investment income earned in non-registered accounts. Think savings accounts, GICs, brokerage accounts, and shares in a private corporation.
You’ll Usually Get One For
- Interest from savings accounts, GICs, and bonds
- Dividends from Canadian public companies
- Dividends from your own corporation
- Foreign income paid through a Canadian institution
You Won’t Get One For
- It’s tax-free, so there’s nothing to report.
- RRSP and RRIF growth (taxed only on withdrawal)
- Mutual fund or ETF trust income (that’s a T3 slip)
The $50 Rule
A payer doesn’t need to issue a slip when the total paid to one recipient for the year is less than $50.
Critical note: No slip doesn’t mean no tax. Investment income is generally taxable even when no T5 is issued. That $32 in savings interest still goes on your return.
How to Read Your T5 Slip
Most T5s only use a handful of boxes. Here are the ones that matter.
| Box | What It Shows | Plain English |
| 13 | Interest from Canadian sources | Your savings and GIC interest |
| 24 | Actual amount of eligible dividends | What you actually received |
| 25 | Taxable amount of eligible dividends | Box 24 grossed up by 38% |
| 26 | Dividend tax credit (eligible) | Your credit to offset the gross-up |
| 10 | Actual amount of other than eligible dividends | Typical small business dividends |
| 11 | Taxable amount of other than eligible dividends | Box 10 grossed up by 15% |
| 12 | Dividend tax credit (other than eligible) | Your credit for Box 11 |
| 18 | Capital gains dividends | Taxed as capital gains |
| 15 and 16 | Foreign income and foreign tax paid | May qualify for a foreign tax credit |
Why the “Gross-Up” Exists
Corporations already paid tax on profits before paying dividends. The gross-up and dividend tax credit work together to avoid taxing the same income twice.
For example: You receive a $1,000 eligible dividend. Box 25 shows $1,380 as taxable income, but Box 26 gives you a credit that knocks a big chunk back off your tax.
How to Report a T5 on Your Return
Good news: if you use certified tax software or CRA’s Auto-fill my return, most T5 amounts drop in automatically. You just need to double-check them.
| T5 Amount | Where It Goes |
| Interest (Box 13) | Line 12100 |
| Taxable dividends (Boxes 11 and 25) | Line 12000 |
| Dividend tax credits (Boxes 12 and 26) | Line 40425 |
| Capital gains dividends (Box 18) | Schedule 3 |
Joint Accounts Need Extra Care
A joint T5 may show 100% of the income, even if two names are on it. Report income based on who contributed the money, not a default 50/50 split.
Lent money to a spouse to invest? CRA attribution rules may push the income back onto your return.
Pro tip: Missing a T5 by April? Don’t wait. Estimate the amount from your bank or brokerage statements, file on time, and adjust later if needed.
How Business Owners Issue T5 Slips
If you pay yourself dividends from your corporation, you’re the T5 issuer. And the CRA expects it done right.
The Key Rules
- Deadline: T5 slips for 2026 are due March 1, 2027, since February 28 falls on a Sunday.
- Copies: Recipients must get their slips by the same date.
- Summary: File a T5 Summary alongside the slips.
- Online filing: Mandatory once you file more than five slips.
Penalties Add Up Fast
| Mistake | Penalty |
| Late filing, 1 to 5 slips | $100 flat |
| Paper filing when online is required (6 to 50 slips) | $125 |
Not sure whether dividends are even the right move? Compare salary vs. dividends before your next draw. Our corporate tax team can prepare and file your T5s alongside your T2, so nothing gets missed at year-end.
Common T5 Mistakes and Fixes
Small errors here create big CRA headaches later.
- Mixing up eligible and non-eligible dividends. Most small business dividends are non-eligible. Getting it wrong changes your tax bill.
- Reporting the actual amount instead of the taxable amount. Line 12000 needs the grossed-up figure.
- Forgetting to issue a slip to a spouse or family shareholder. Every recipient at $50 or more needs one.
- Ignoring amended slips. If your brokerage sends a corrected T5, update your return.
- Skipping capital dividends’ paperwork. These aren’t reported on a T5 at all. They need a separate CRA election.
Already filed with a wrong T5? Use Change my return in CRA My Account. And if a T5 was issued late from your corporation, see what happens with late tax filing before penalties stack up.
Get Every T5 Right With NRK Accounting
T5 slips look intimidating, but they follow a simple logic. The actual amount is what you received, the taxable amount is what you report, and the credit evens things out. Get those three right, and you’re most of the way there.
Key takeaways:
- A T5 reports interest and dividends from non-registered investments.
- Income under $50 still needs to be reported, slip or not.
- Taxable dividends go on line 12000, interest on line 12100.
- Corporations must issue 2026 T5s by March 1, 2027.
- More than five slips means mandatory online filing.
From reporting your investment income to issuing T5s from your own corporation, NRK Accounting keeps it accurate and on time. Book a free consultation or call 416-577-4301 before slip season sneaks up on you.
Frequently Asked Questions
What is a T5 slip used for?
A T5 slip reports interest, dividends, and certain other investment income paid to you. You use it to report that income on your tax return.
Do I have to report income if I didn’t get a T5?
Yes. Investment income is taxable even without a slip. Payers only issue T5s when annual payments to you reach $50 or more.
When are T5 slips issued?
T5 slips for the 2026 tax year must be issued and filed by March 1, 2027, because February 28 falls on a Sunday.
What is the difference between a T5 and a T3 slip?
A T5 reports investment income from banks and corporations. A T3 reports income from trusts, including most mutual funds and ETFs.
Do I need to issue a T5 if I pay myself dividends?
Yes. If your corporation pays you $50 or more in dividends during the year, it must issue a T5 slip and file a T5 Summary.